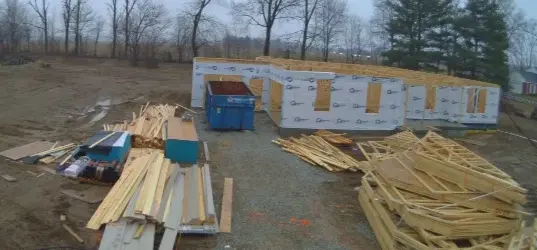
Financing for experienced and new builders alike—including strong first-time ground-up construction programs for investors with fix-and-flip experience—with options that can include land acquisition and construction costs.
Land acquisition and vertical construction financing
02
Programs for experienced builders and qualified first-time ground-up projects
03
Draw-based funding aligned with construction progress
04
Underwriting that considers budget, timeline, experience, and completed value
Ground-up construction explained
Capital structured around the complete build.
Ground-up construction financing provides short-term, business-purpose capital to acquire eligible land and build a new investment property. Programs are available for experienced builders as well as qualified new builders whose successful fix-and-flip work demonstrates that they can manage budgets, contractors, schedules, inspections, and a profitable exit.
01
Land, construction, and draws
The loan may include an approved portion of the land acquisition and eligible hard and soft construction costs. Construction funds are generally held back and released through draws as work is completed and verified. Underwriting reviews the plans, permits, budget, contractor structure, schedule, completed value, and the strategy for selling or refinancing the finished property.
02
Experience affects leverage
Programs up to approximately 90% loan-to-cost may be available to the most experienced builders with strong credit, liquidity, and a proven record of comparable completed projects. Builders with less ground-up experience should expect lower leverage, meaning a larger cash or land equity contribution may be required.
03
Pricing reflects execution risk
Less-experienced ground-up construction applicants should also expect a higher rate or additional pricing compared with seasoned builders. Strong fix-and-flip experience, adequate reserves, a realistic budget, an experienced general contractor, and a well-supported exit can help strengthen a first ground-up construction request.
LTC limits, rates, fees, reserves, draw procedures, eligible costs, and experience requirements vary by lender and project. Up to 90% LTC is not available for every borrower or transaction; final terms are determined after a complete review of the builder, property, budget, and exit.
Every deal is different
Let’s review yours.
Share the property, scope, experience, timing, and exit strategy. We’ll help identify the clearest path forward.